Wind damage
Creases, torn tabs and displaced shingles show how the covering has moved. A broken seal can leave an edge vulnerable even when the shingle is still attached.
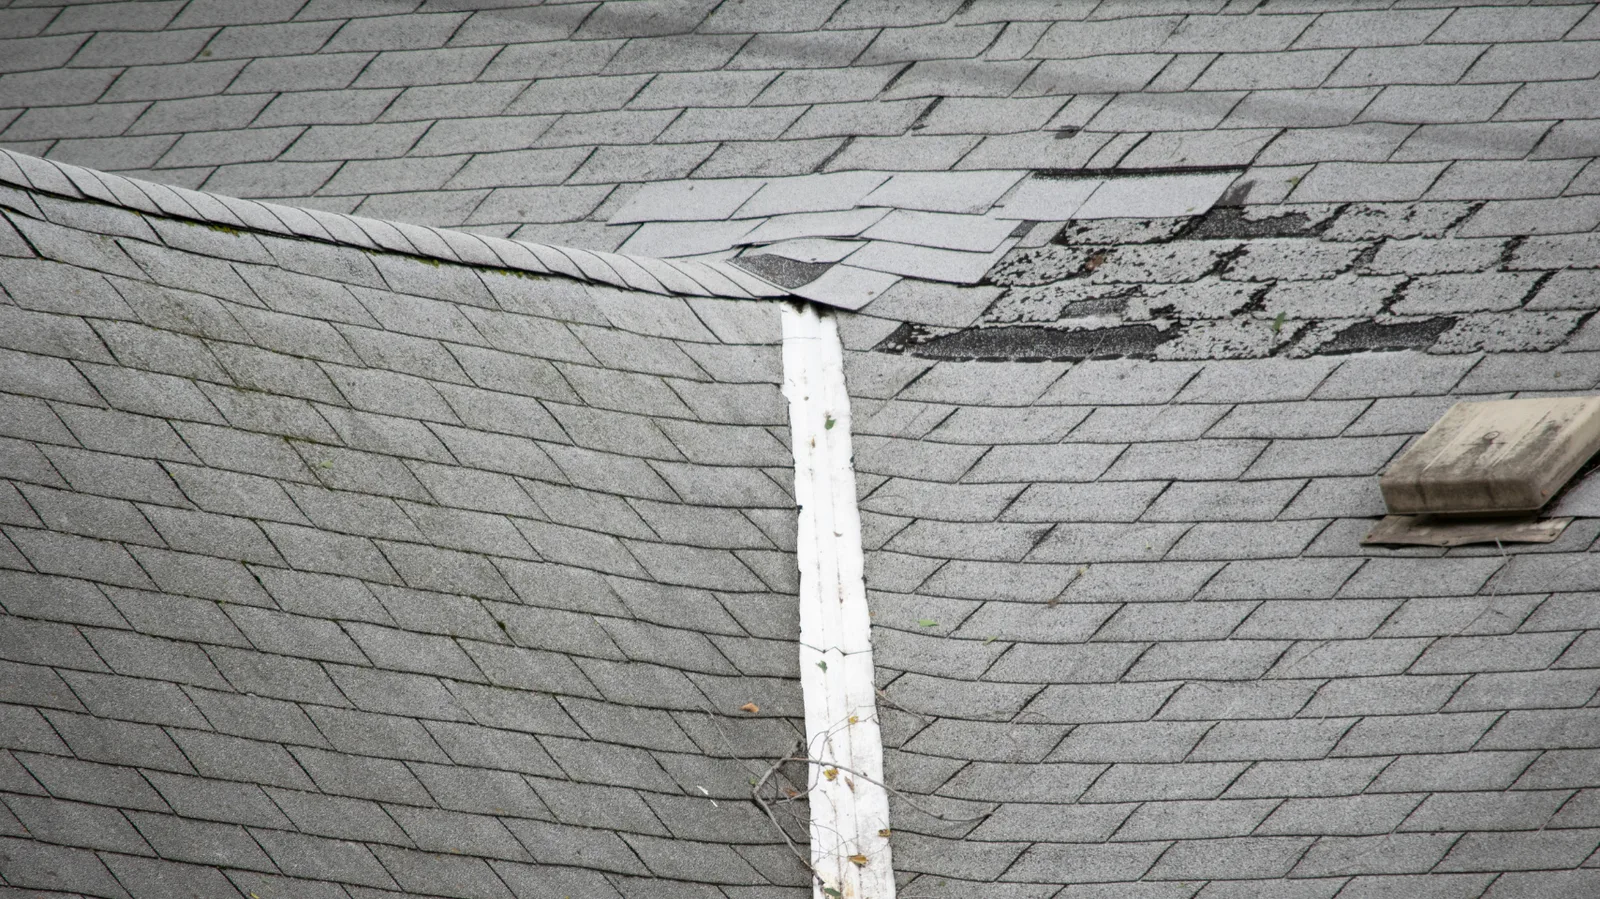
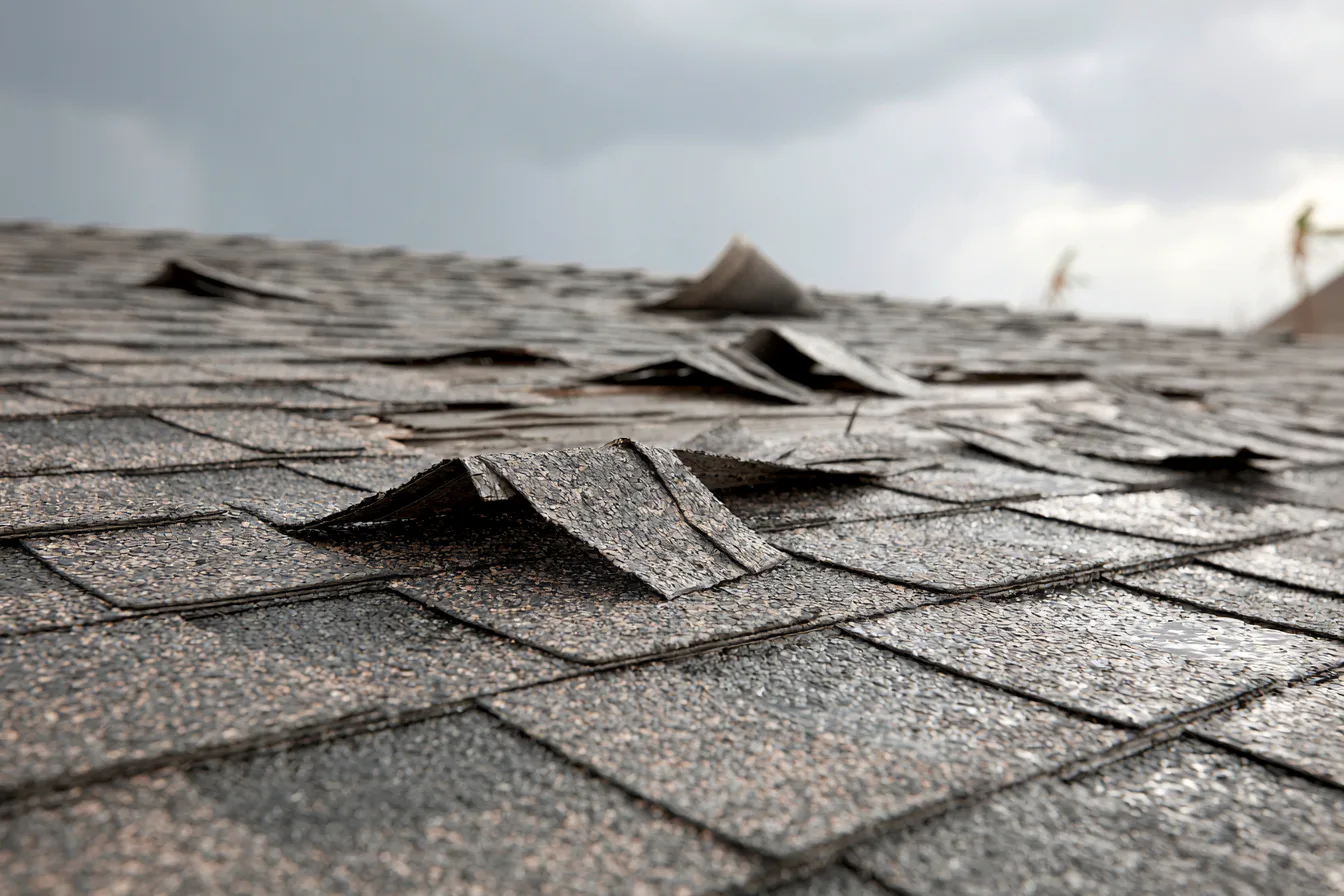
Missing shingles, hail marks or a roof opening after severe weather deserve a closer look. Start with safe protection and a roof inspection, then work out the permanent repair.
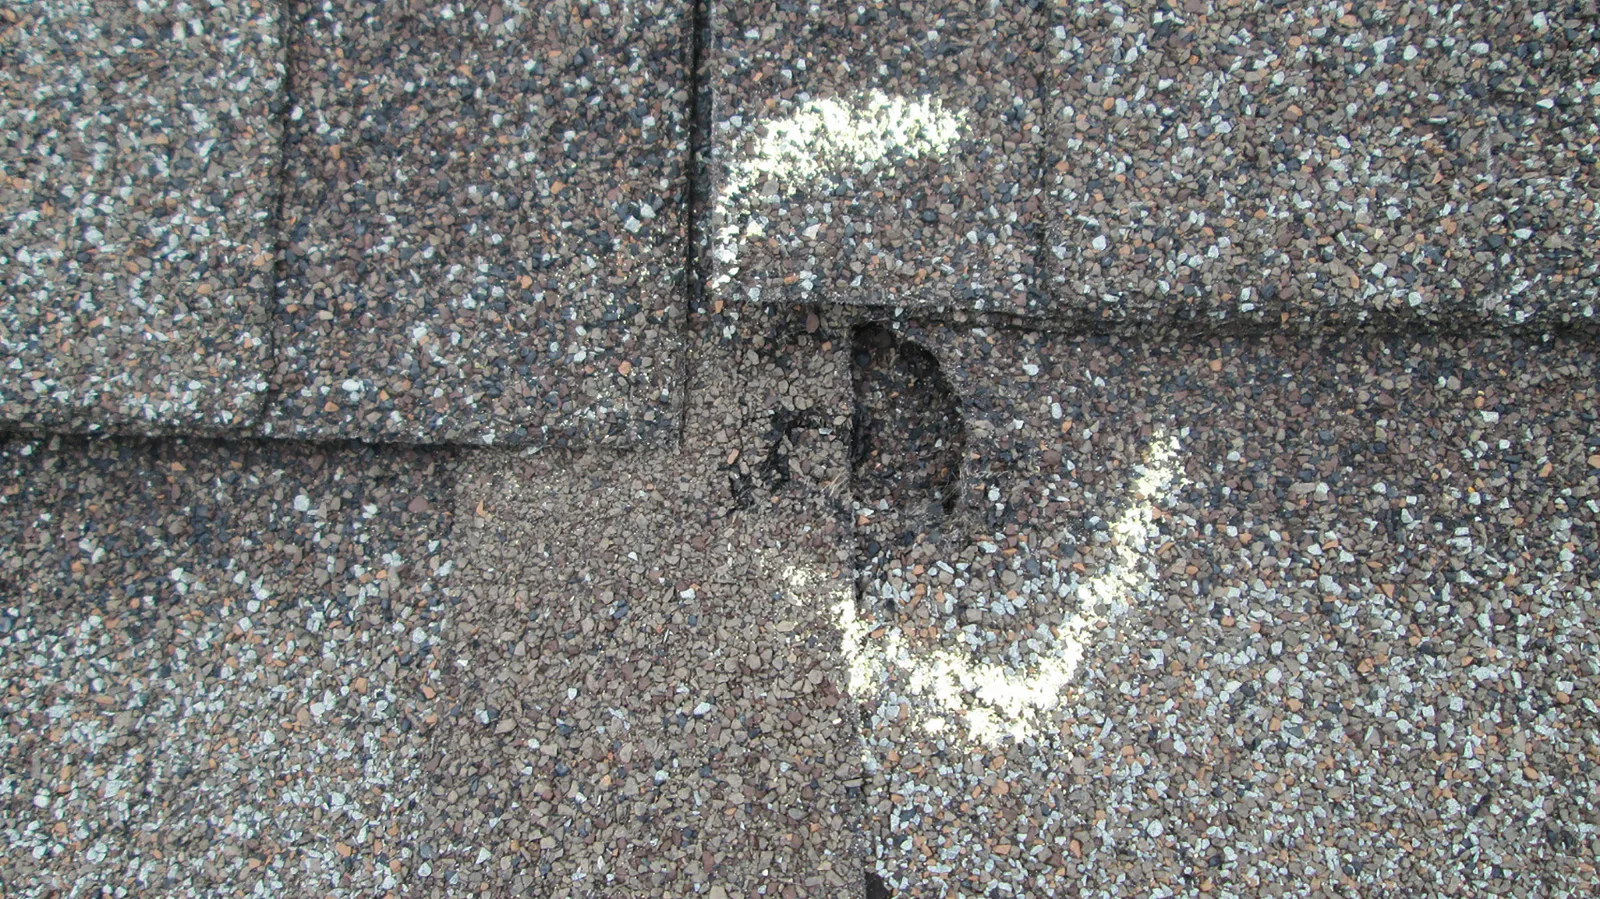
Wind can lift a shingle edge and break its seal without carrying the whole shingle into the yard. Hail can damage the shingle surface or reinforcement without making a visible hole. The absence of an indoor leak does not answer the condition of those materials.
A free storm-damage inspection in Midwest City looks at the roof itself. It does not establish which storm caused a mark or decide insurance coverage. When the damage is local, a roof repair can be the right scope.
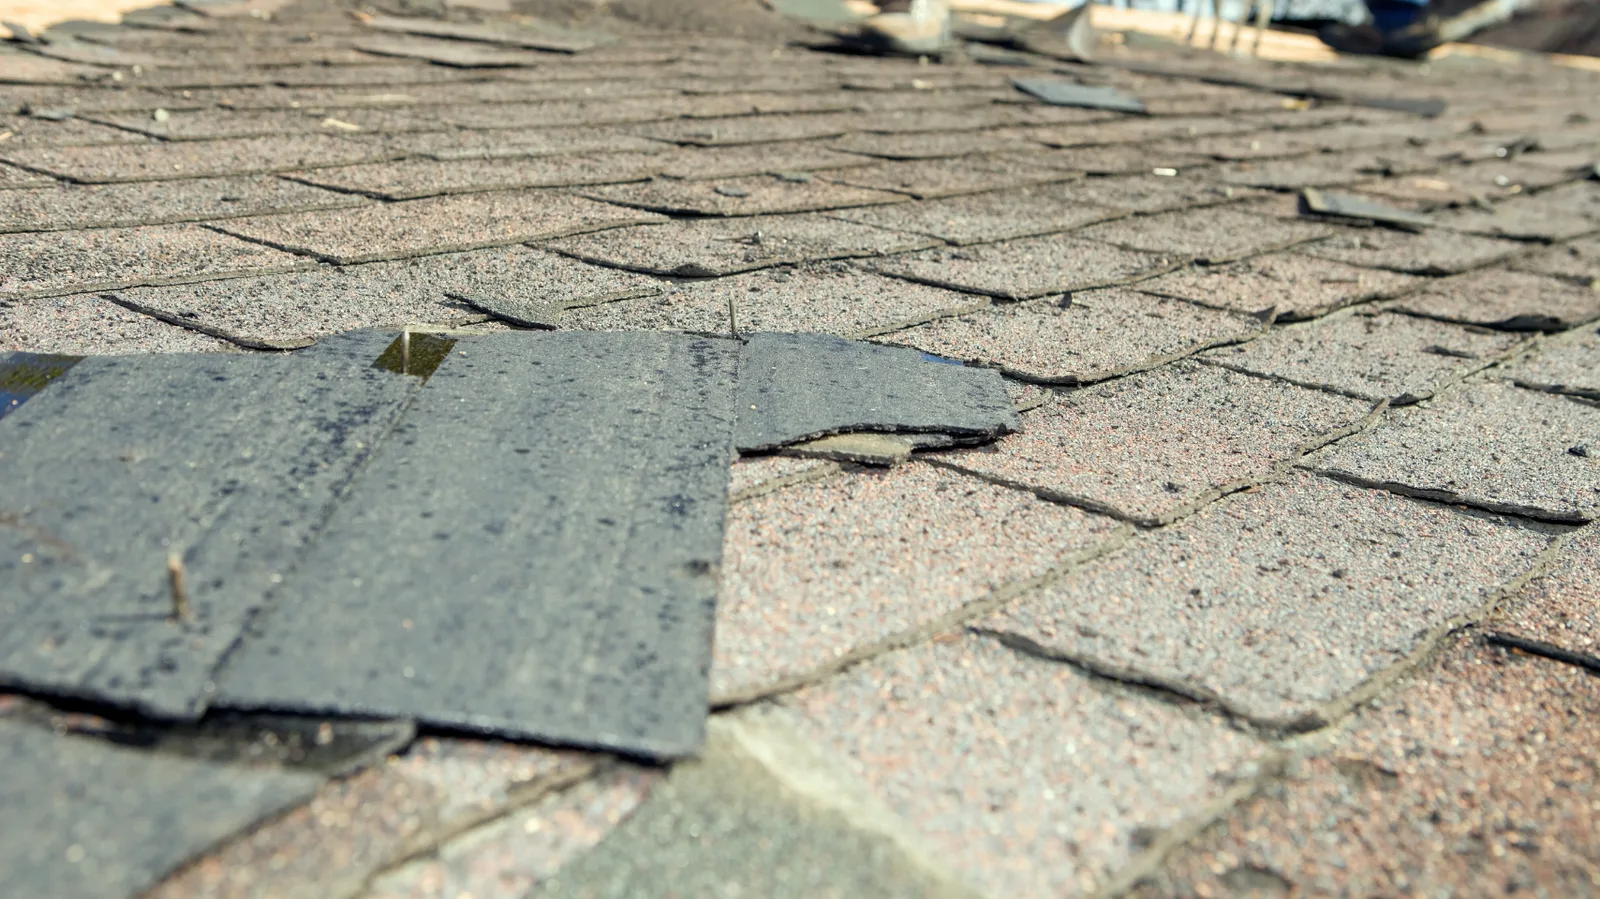
The inspection puts the marks in the context of the covering and its condition.
Creases, torn tabs and displaced shingles show how the covering has moved. A broken seal can leave an edge vulnerable even when the shingle is still attached.
An impact can dislodge granules and injure the shingle beneath them. Marks on other roof surfaces help the inspection, but do not establish damage to every shingle.
Downed lines, unstable branches, roof openings and wet electrical fixtures call for immediate safety decisions. Stay off the roof.
The condition of the covering and surrounding material defines the repair options. Temporary protection and permanent work are separate parts of the conversation.
For a claim, the insurer decides coverage under the policy. Our insurance-payment guide explains deductibles and depreciation before the figures get confusing.
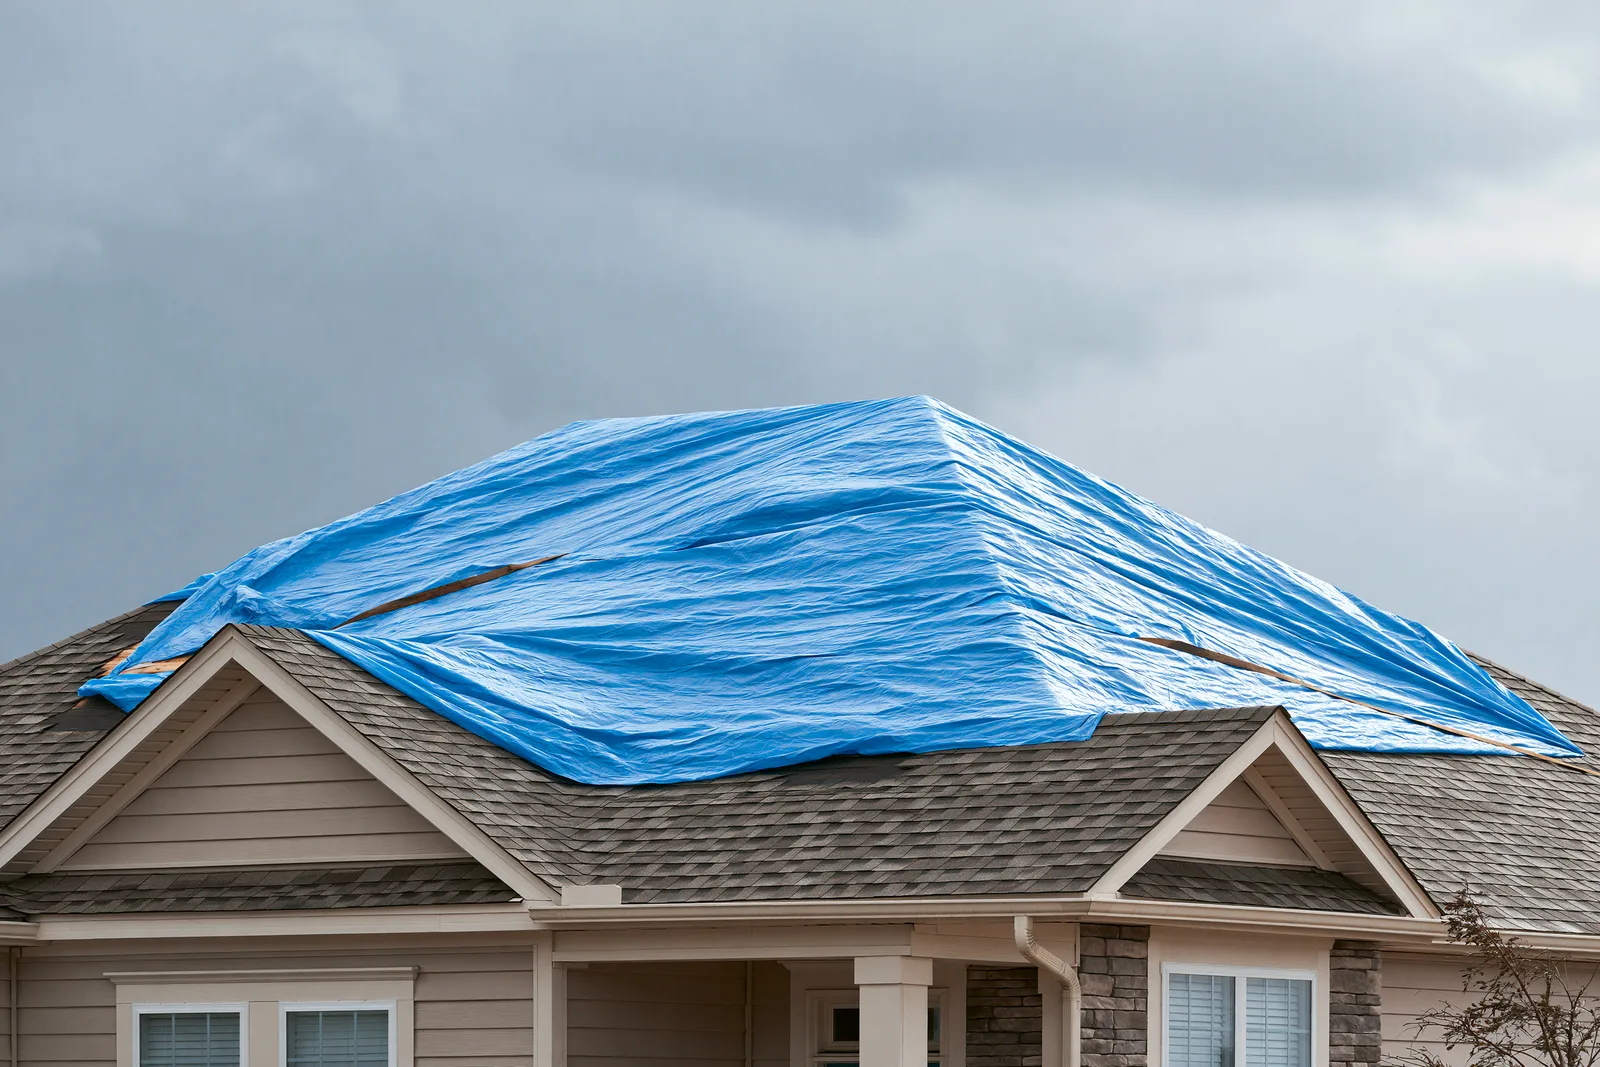
A properly arranged tarp can reduce additional water entry while the roof awaits repair. It cannot restore damaged decking or replace a complete flashing detail. Its attachment and removal need to avoid adding damage to sound roof material.
The Oklahoma Insurance Department advises protecting property against further loss and retaining repair records. Keep any photos you already took safely; do not climb onto the roof to create evidence.
No. Damage, policy coverage, exclusions, deductible and the insurer’s assessment all matter. A reported hail event is not proof of damage at an individual property, and an inspection is not a coverage decision.
Yes. The current roof condition is still useful to understand. It may not establish the date of damage. Claim reporting and repair deadlines come from the policy and insurer, so those timing questions belong with them.
The deductible is the policyholder’s share under the claim terms. Recoverable depreciation is a separate item. See how roof insurance payments fit together for a clearly labeled example.
Tell us what you noticed and where the property is. A free inspection can help separate the damage from the next decision.